Shop
Market Pulse

Body Art & Piercing Studio Insurance: What You Actually Need

PP

Chief Engineer

Patrick Poli

Journal Date

2026-07-14

Last Reviewed

2026-10-20

Why Every Body Art Studio Needs Insurance Coverage That Actually Fits

A tattoo or piercing studio operates at the intersection of risk categories that general business insurance was never designed to handle. You are breaking the skin of paying clients with sharp instruments, inserting foreign materials into healing wounds, and maintaining an environment where cross-contamination can mean bloodborne pathogen exposure. A standard retail or office policy will exclude body art procedures by default because the underwriter knows the risk profile is fundamentally different.

Key Takeaways:

» General liability covers third-party injury and property damage, but does not cover the procedure itself, that gap is professional indemnity, and it is the most common coverage failure in body art studios
» Professional indemnity policies operate on a claims-made basis, meaning the policy in force when the claim is made responds, not when the incident occurred, requiring run-off cover after retirement
» Documentation is your best claims defence: client health screening forms, signed consent, aftercare instructions, and material certificates are evidence that you met the standard of care
» Underinsurance triggers the average clause, if you insure for 50% of your replacement value, the insurer pays 50% of the claim, making annual equipment inventories non-negotiable
» Product liability exposure is separate from professional service exposure, and your defence rests on traceability to batch-certified manufacturers
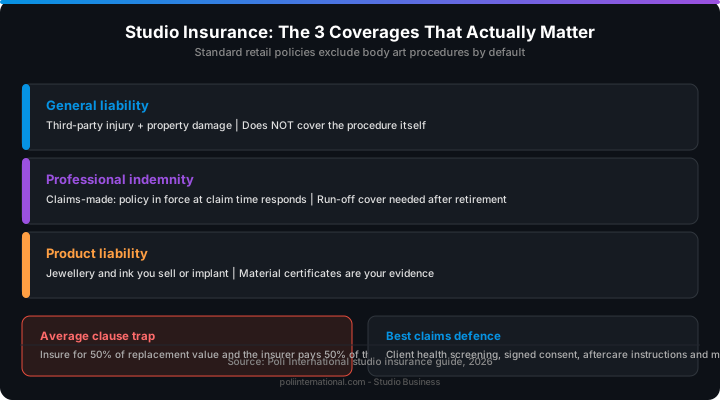
Studio insurance coverage comparison: general liability, professional indemnity and product liability
Infographic: Studio insurance coverage comparison: general liability, professional indemnity and product liability

1. General Liability: The Floor, Not the Ceiling

General liability (public liability in UK/AU terminology) covers third-party bodily injury and property damage. If a client trips on your doorway, if a shelf collapses onto their belongings, if your signage falls and injures a passerby, this is general liability territory. Typical limits range from £1 million to £10 million depending on jurisdiction and landlord requirements.

What general liability does not cover is the procedure itself. The moment a claim turns on the quality, outcome, or professional standard of a tattoo or piercing, you are no longer in general liability territory. That is professional indemnity, and a gap between the two is the single most common coverage failure in body art studios.

Landlords increasingly require named-insured status on studio liability policies, meaning they want to be listed on the certificate as an additional insured. This is straightforward to arrange with most insurers but must be requested explicitly. A landlord that demands this mid-lease and is refused has grounds for default.

2. Professional Indemnity: The Policy That Protects Your Work

Professional indemnity (malpractice insurance, errors and omissions) covers claims that your professional service caused harm or loss. In body art, this means a tattoo that heals poorly and requires medical treatment, a piercing placed incorrectly causing tissue damage, a pigment reaction the client claims you should have anticipated, or scarring or keloid formation attributed to your technique rather than the client's physiology.

The standard of care matters. Underwriters assess claims against what a reasonable professional in the same circumstances would have done. This is why documentation is your best defence: client health screening forms, signed consent documents, aftercare instructions provided in writing, material certificates for the jewellery and inks used. Every piece of paper in your client file is evidence that you met or exceeded the standard of care.

Professional indemnity policies typically operate on a claims-made basis, meaning the policy that responds is the one in force when the claim is made, not when the incident occurred. This has a practical implication: if you retire or close your studio, you need run-off cover (also called tail coverage) to protect against claims that arise after you stop practising. A client can develop a delayed hypersensitivity reaction two years after a piercing. Without run-off cover, you are personally exposed.

3. Property, Stock, and Business Interruption

Body art studio equipment costs more than most owners realise until they try to replace it all at once. An autoclave (£2,000 to £8,000), tattoo machines (£200 to £1,200 each, and a working studio may have five to fifteen), power supplies, ultrasonic cleaners, furniture, lighting, and stock can total £20,000 to £50,000 for a modest studio.

Two common pitfalls in property coverage deserve attention. Underinsurance: if you insure for £15,000 and suffer a £30,000 loss, most policies apply the average clause (condition of average), reducing the payout proportionally. You insured 50% of the value, so you receive 50% of the claim, minus the excess. New-for-old versus indemnity basis: a new-for-old policy replaces your five-year-old autoclave with a new equivalent model. An indemnity policy pays the depreciated value, which for a five-year-old autoclave might be 30% of replacement cost. The premium difference is modest; the payout difference at claim time is not.

Stock coverage deserves specific attention. Body jewellery is small, high-value, and portable. A single display case of implant-grade titanium barbells and labrets can hold £3,000 to £8,000 in stock. If your policy has a low sub-limit on stock or excludes valuable metals, you have a coverage gap. Discuss stock explicitly with your broker, itemising the type and value of jewellery, inks, and needles you hold.

Business interruption insurance covers the income you lose when the studio cannot trade due to an insured event. It typically pays a percentage of your average weekly or monthly gross revenue, plus continuing fixed costs, for a defined period: twelve months is standard, twenty-four is available at higher premium.
From the Chief Engineer's Workbench

Patrick Poli · 25+ years in body-jewellery manufacturing

Patrick’s Deep Archive

I have spent thirty years watching companies insure the wrong things. In materials engineering, you learn to identify the failure mode before you design the fix. Insurance for a body art studio is the same discipline applied to liability rather than tensile strength. The mistake I see repeatedly is studios buying the minimum cover the landlord or licensing authority demands and calling it done. That is like specifying a safety factor of 1.0 on a component that holds a person's weight, it satisfies the letter of the requirement and fails catastrophically the first time the real world exceeds the design assumption.

The real world, in a tattoo or piercing studio, is a client who develops a nickel sensitivity two years later and instructs a solicitor. It is an autoclave that fails on a busy Saturday and forces a week of cancelled appointments. It is a flood that destroys your stock and forces a three-month rebuild. The premium for adequate cover, public liability at £5 million rather than £1 million, professional indemnity at £1 million rather than £250,000, is rarely the difference between a viable business and a failing one. The gap between adequate and inadequate cover, however, is the difference between a claim that closes your studio and a claim you survive.

I also want to say something about documentation that insurance brochures never say. Every client health screening form, every signed consent, every aftercare sheet you hand to a client and record in their file, is an engineered defence. It is a material cert for your process. When an insurer's claims handler reviews a file and sees a documented trail of informed consent, material traceability, and written aftercare instructions, the claim posture changes. You are no longer defending your word against the client's. You are presenting a quality system.

PPPatrick PoliChief Engineer · Creator of BioFlex® body jewelry

5. FAQ

Do I need insurance if I am a sole trader working from a private studio? Yes. Operating as a sole trader does not reduce your liability exposure; it increases your personal exposure because there is no limited company between you and a claim. Public liability is typically a licensing condition regardless of business structure. Professional indemnity protects your personal assets against claims arising from your work.

Does my insurance cover me when I guest-spot at another studio or work a convention? Not by default. Most studio policies are premises-specific: they cover procedures performed at the insured address during normal business hours. Guest spots, conventions, and offsite work require a specific extension or a separate temporary policy. Do not assume the host studio's policy covers you, it almost certainly does not.

What should I do if a client threatens to sue? Notify your insurer immediately. Do not admit liability, do not offer compensation, and do not discuss fault with the client. Pull the client file (health screening, consent forms, aftercare instructions, material certificates, procedure notes) and keep it secure. Delaying notification can prejudice your cover: policies require prompt notification of circumstances that may give rise to a claim.

How much does body art studio insurance cost? A combined liability policy (public liability, professional indemnity, and product liability) for a single-artist UK studio typically costs £400 to £1,200 per year depending on turnover, procedures performed, and claims history. US premiums vary widely by state and coverage limits but typically range from $800 to $3,000 annually.

Is there body-art-specific insurance, or do I use a standard business policy? You need a policy that specifically covers body art procedures. A standard business insurance policy will almost certainly exclude any procedure that breaks the skin. Specialist brokers exist in most markets. Do not accept a generic policy that does not explicitly list tattooing or body piercing as covered activities.

Conclusion

Studio insurance is not a compliance checkbox. It is the last line of a complete safety posture. You control what you can: sterilisation protocols, material certification, client screening, documentation. Insurance covers what you cannot control: the delayed hypersensitivity reaction, the equipment failure on a fully booked Saturday, the flood that closes your doors for months. The difference between adequate cover and minimum cover is not measured in premium pounds, it is measured in whether your studio survives its first serious claim. Document everything, review your cover annually against your actual equipment and stock values, and when in doubt, ask a specialist broker who understands body art, not a general business insurer who does not.

6. Body Art and Body Piercing Insurance: Matching Coverage to Your Actual Risk

The search queries that bring people to this page tell me something useful: most studio owners are not looking for a generic business policy. They are looking for body art insurance and body piercing insurance specifically, two phrases that describe a risk profile general insurers consistently underestimate. A body art policy needs to account for skin penetration, bloodborne pathogen exposure, allergic reaction to pigments and metals, and the reputational fallout of a botched procedure. A piercing-specific policy adds its own layer: jewellery quality, sterilisation protocols, and aftercare advice all become potential liability triggers if something goes wrong.

When I created BioFlex® body jewelry more than 25 years ago, one of the first conversations I had with studio owners was about exactly this. They told me their insurer had asked whether they used "hypoallergenic jewellery" and they had no idea how to answer, because the term means nothing legally. I have sat in on enough claims discussions since then to know that the material you implant is not a side issue in an insurance assessment, it is central. If you cannot document the polymer grade, the REACH compliance status, and the traceability of every piece you insert, you are handing your insurer a reason to dispute a claim. That is not a scare tactic. It is what happens when paperwork meets a real allergic reaction.

So what should you actually look for? First, confirm that your professional indemnity policy explicitly names body art or body piercing as a covered activity, not "beauty treatments" or "personal care services." Second, check whether product liability extends to the jewellery and pigments you supply, not just the service you perform. Third, ask about treatment risks: does the policy cover complications arising from a procedure, or only from your premises? Fourth, verify that business interruption cover accounts for the downtime after a bloodborne pathogen incident, which can shut a studio for days. Fifth, and this is the one most owners miss, make sure your consent and aftercare documentation is referenced in your risk management schedule. Insurers price behaviour, not just hazards.

The practical takeaway is simple: your insurance is only as strong as the evidence behind it. Use only traceable, compliant materials, keep batch records, and document every aftercare instruction you give. If you want to see how BioFlex® supports that documentation chain, including REACH compliance and material traceability, start with our BioFlex® polymer range. And if you are auditing your studio's risk controls, our studio tools and documentation guides will help you build the paper trail your insurer actually wants to see.

Mind map · Body Art & Piercing Studio Insurance: What You Actually Need

  • Body Art Studio Insurance
    • General Liability

      General liability insurance covers physical accidents and third-party property damage on the studio premises.

      • Premises Liability
      • Slip and Fall
      • Landlord Requirements
    • Professional Liability

      Professional liability covers claims about the quality of tattoo work, including infections, allergic reactions, and design errors.

      • Procedure Outcomes
      • Claims-Made Structure
      • Run-Off Cover
    • Commercial Property

      Commercial property insurance covers your buildings, equipment, and inventory.

      • Autoclaves and Machines
      • High-Value Stock
      • Business Interruption
    • Workers' Compensation

      California law mandates workers' compensation insurance to protect employees and meet state requirements.

      • Repetitive Strain
      • Needlestick Incidents
      • Contractor Testing
    • Risk Documentation

      Consent forms, questionnaires, and sterilization logs support the legal defense if client negligence allegations arise.

      • Signed Consent Forms
      • Sterilization Logs
      • Aftercare Instructions
StructureProcessMaterialHazard

5 branches, 0 sources. Each branch cites the article it came from; the labels beneath it are names, not claims.

Body Art Insurance Quiz

  1. 1. What is the main coverage gap when a body art studio relies solely on general liability insurance?

    • ✓ General liability covers premises-related injuries, but excludes claims arising directly from the procedure itself. — General liability protects against third-party accidents on site, whereas treatment outcomes fall under professional indemnity.
    • • General liability only covers equipment failure, excluding third-party slip-and-fall incidents. — General liability specifically covers slip-and-fall accidents while excluding procedure-related harm.
    • • General liability covers property damage caused by artists, but excludes client property damage. — Public and general liability policies cover third-party bodily injury and property damage, but ignore professional service failures.
    • • General liability only applies to sole traders, leaving limited companies uninsured for procedures. — Liability policy applicability depends on coverage terms rather than corporate structure, though procedure risks are consistently excluded across business types.
  2. 2. What type of insurance policy is required to protect a studio owner against delayed hypersensitivity claims made after they have retired or closed their business?

    • • A new-for-old indemnity policy. — New-for-old coverage applies to physical property replacement rather than post-closure professional service claims.
    • ✓ Run-off cover (tail coverage). — Run-off cover maintains protection against claims filed after a studio closes or an artist retires for procedures performed while active.
    • • Premises-specific public liability extension. — Premises extensions cover location variations during active operation rather than claims filed after operations cease.
    • • Product liability average clause. — The average clause is a penalty calculation for underinsurance, not a policy extension for post-retirement liability.
  3. 3. Under the average clause (condition of average), what payout would a studio receive if they insured £15,000 worth of equipment against a total actual replacement value of £30,000 and suffered a £10,000 loss?

    • • £10,000 minus excess, because the loss was under the insured total of £15,000. — Underinsurance penalties apply proportionally across all claims rather than paying full value up to the insured sum limit.
    • ✓ £5,000 minus excess, because insuring 50% of total value reduces claim payouts to 50%. — Under the average clause, insuring half of the total replacement value results in receiving only half of any claim payout, regardless of the claim amount.
    • • £15,000 full compensation, as long as the claim occurred within the standard 12-month period. — Insurers reduce payouts proportionally based on the ratio of insured value to actual value rather than paying out the full limit.
    • • £3,000 minus excess, calculated as 30% depreciated value under indemnity rules. — Depreciated value rules apply to indemnity adjustments on aged items rather than proportional underinsurance calculations.
  4. 4. How does a "new-for-old" property policy differ from an "indemnity basis" property policy when replacing aging studio equipment like an autoclave?

    • • New-for-old pays the depreciated value of the old equipment, while indemnity replaces it with a brand-new model. — This reverses the definitions, as indemnity pays depreciated value and new-for-old provides modern replacements.
    • • New-for-old requires an annual inventory audit, whereas indemnity policies automatically adjust for inflation. — Inventory audits are essential for avoiding underinsurance regardless of whether property is insured on a new-for-old or indemnity basis.
    • ✓ New-for-old replaces the item with a new equivalent model, whereas indemnity pays the depreciated market value. — New-for-old policies fund full replacement with modern equivalents, while indemnity policies deduct value based on usage and age.
    • • New-for-old covers property damage during travel, whereas indemnity only covers items on the studio premises. — Both policy types address physical asset valuation methods rather than geographical coverage boundaries.
  5. 5. Why is a standard studio insurance policy typically insufficient for an artist participating in a convention or guest spot at another studio?

    • ✓ Most policies are premises-specific and only cover procedures performed at the listed studio address. — Standard policies restrict coverage to the specific studio address noted on the policy unless an explicit offsite endorsement is added.
    • • Standard policies strictly prohibit artists from operating outside their home country. — Offsite limitations apply even to local guest spots within the same city, not just international travel.
    • • Host studios are legally required to absorb all liability for visiting guest artists. — Host studio policies almost certainly exclude visiting artists, leaving unendorsed guest artists personally exposed.
    • • Public liability automatically transfers to the convention venue, but professional indemnity is voided. — Neither general liability nor professional indemnity transfers automatically to external event venues or host studios.
  6. 6. What immediate action should a studio owner take if a client threatens to take legal action over a procedure?

    • • Offer a partial refund and an apology to resolve the dispute amicably before contacting insurers. — Admitting fault or offering compensation before notifying the insurer can breach policy terms and invalidate coverage.
    • ✓ Immediately notify the insurer, avoid admitting liability or offering compensation, and secure the complete client file. — Prompt notification and preservation of records without admitting fault protect policy coverage and establish a proper legal defense.
    • • Destroy older client screening forms to simplify the legal file presented to solicitors. — Client documentation provides the essential evidence that the standard of care was met, and destroying records severely compromises legal defense.
    • • Transfer the claim to the host studio’s public liability policy to cover initial legal expenses. — Claims cannot be arbitrarily transferred to third-party policies, which typically exclude independent visiting artists anyway.
  7. 7. Why is relying on generic terms like "hypoallergenic jewellery" problematic during an insurance claim assessment?

    • • The term "hypoallergenic" is a strict legal standard that requires expensive third-party lab verification for every piece sold. — The term lacks a standard legal definition entirely, which is why insurers look for verified polymer grades and batch traceability instead.
    • • Insurers view "hypoallergenic" as a guarantee of zero allergic reactions, increasing studio premiums automatically. — Insurers discount vague terminology because it provides no verifiable evidence of material safety during liability disputes.
    • ✓ The term has no legal definition, whereas insurers require specific material traceability, polymer grades, and compliance documentation. — Generic claims lack legal standing during claim reviews, requiring documented proof of REACH compliance and material grades to substantiate safety.
    • • Health regulators strictly ban the use of non-metallic materials in all body art and piercing procedures. — Non-metallic materials like BioFlex® polymers are used in body piercing provided they meet REACH and material safety standards.
  8. 8. Which statement correctly describes the nature of professional indemnity policies in the body art industry?

    • • They operate on an occurrence basis, covering any incident that took place while the policy was active regardless of when claimed. — Occurrence-based policies are uncommon in professional indemnity, which standardly relies on claims-made structures requiring continuous or run-off cover.
    • ✓ They operate on a claims-made basis, meaning the policy active at the time the claim is filed responds to the claim. — Claims-made policies cover liability based on when the legal claim is brought forward rather than when the procedure occurred.
    • • They are included by default in basic retail and commercial property insurance packages. — Standard business policies routinely exclude skin penetration procedures, requiring specialist professional indemnity coverage.
    • • They primarily cover slip-and-fall injuries and building signage collapses on the studio premises. — Slip-and-fall accidents fall under general public liability rather than professional indemnity.
  9. 9. What does business interruption insurance typically cover for a body art studio?

    • • Payouts for damage caused by worn-out tattoo needles and autoclaves during normal operating hours. — Business interruption compensates for lost trading income due to covered events, not routine equipment maintenance or wear.
    • • Medical expenses and compensation paid directly to injured clients following a botched procedure. — Client medical expenses stemming from bad procedure outcomes are handled under professional indemnity, not business interruption.
    • ✓ Lost gross revenue percentage and continuing fixed costs when the studio cannot trade due to an insured event. — Business interruption compensates for continuous fixed overhead and lost earnings during mandatory operational downtime caused by insured disasters.
    • • Legal defense fees specifically for copyright infringement claims on tattoo designs. — Business interruption focuses on studio revenue and fixed overhead recovery following physical or operational disruptions.
  10. 10. What role does complete client documentation (such as health screening, consent, aftercare, and material certificates) play in defending against a lawsuit?

    • • It eliminates the need for professional indemnity insurance by transferring all legal liability to the client. — Written consent and screening demonstrate due diligence, but they do not replace the need for professional indemnity insurance.
    • ✓ It proves that the studio maintained a quality system meeting or exceeding the standard of care. — Comprehensive client records transform subjective word-against-word disputes into documented proof of professional standard adherence.
    • • It guarantees that the insurer will pay 100% of property claims without applying an excess fee. — Client records pertain to professional liability claims defense rather than property loss valuations or policy excesses.
    • • It legally prevents clients from filing claims for delayed hypersensitivity reactions. — Client documentation provides evidence for defending against hypersensitivity claims, but cannot legally bar a client from bringing a suit.

Extended Reference Table

8 of 8 rows

Extended reference table generated from the article and its verified research sources. Bracketed numbers jump to the matching entry in the Technical References below.

SafetyItem, Practice, or Standard Category Description and Regulatory Significance Applicable Standards or Compliance Requirements Source
✅Bloodborne Pathogens StandardRegulatory StandardMandates written exposure control plans, annual training, and the use of sterile equipment/sanitized tools to prevent the spread of infections like HIV or Hepatitis. Includes management of needlestick incidents and puncture wounds.OSHA 29 CFR 1910.1030
✅Tattoo Ink PigmentsMaterialsChemical substances used for tattooing (including red and yellow pigments) that can cause allergic reactions or adverse effects. Regulation focuses on ingredient safety and batch traceability to mitigate product liability.FDA Regulations; Federal Food, Drug, and Cosmetic Act; Regulation (EU) 2020/2081
✅Workers' Compensation InsuranceRegulatory ComplianceMandatory insurance for studios with employees to cover medical costs, lost wages, and disability for work-related injuries, including repetitive strain and needlestick incidents.California AB5; State Labor Laws; State Workers' Compensation Statutes
✅General Liability InsuranceRisk ManagementCovers third-party bodily injury (such as slip-and-fall accidents) and property damage occurring on the business premises. Often required by landlords or for business licensing.Standard Commercial General Liability (CGL) forms; Municipal Requirements
✅Professional Liability InsuranceRisk ManagementAlso known as Errors & Omissions or malpractice insurance; covers claims regarding the work itself, including infections, scarring, nerve damage, permanent disfigurement, or artistic dissatisfaction.State Licensing Board Requirements; Professional Standards of Care
✅Autoclave SterilizationClinical PracticeUse of pressurized steam and ultrasonic cleaners to sterilize reusable equipment. Proper function must be documented to defend against infection claims.EN 13060; Health Department Sanitation Protocols
✅Hepatitis B VaccinationHealth Safety PracticeEmployers are required to offer the vaccination series to all employees with occupational exposure risk within 10 working days of initial assignment.OSHA 29 CFR 1910.1030
✅Repetitive Stress Injury PreventionHealth Safety PracticeImplementation of ergonomic practices to prevent long-term physical damage to artists, such as carpal tunnel syndrome, which are compensable under labor laws.OSHA General Duty Clause Section 5(a)(1)

Free Body Art Wall Posters

Print-ready reference posters for your studio or your own wall. Free to download and display, embed on your own site with attribution. Click any poster to preview it full size before downloading.

Choose and download all 40 posters

Technical_References_Archive

  • [1]UK Health and Safety Executive, Employers' Liability (Compulsory Insurance) Act 1969, hse.gov.uk/pubns/hse40.pdf
  • [2]Association of Professional Piercers (APP), Studio Insurance Guidelines, safepiercing.org
  • [3]Alliance of Professional Tattooists (APT), Insurance Resources for Tattoo Artists, safe-tattoos.com

About the Author

PP

Patrick Poli

Chief Engineer, Poli International · Creator of BioFlex® body jewelry

Patrick has spent 25+ years manufacturing body jewellery and studio equipment, and is the creator of BioFlex® body jewelry. He founded Poli International with his son Frédéric to work on recyclable and bio-friendly materials for tattoo and piercing. He also made custom titanium body jewellery in metric sizes the market still does not offer, because manufacturers stop at 2 mm steps and a piercing rarely fits a round number.

More about Patrick →

Last reviewed: 2026-10-20 · Published: 2026-07-14

Related Tools & Reading

Continue Reading